WHOLE OF MARKET MORTGAGE ADVICE
Buying - Remortgage
Further Borrowing - Buy to Let
Insurance - Protection
Whole of Market Mortgage Advice
Oakdene Mortgages are independent, whole-of-market mortgage and protection brokers serving clients In Brighton & Hove, East & West Sussex and across the UK. We’re proud to have built a reputation for excellent service, with 5-star reviews from clients who value our approachable style and expert knowledge. From first-time buyers navigating their first purchase to landlords building their portfolio, we combine experience with genuine care to ensure you feel confident and supported throughout the process. All with no Broker Fees
MORTGAGES
MORTGAGES
Whether you are a first time buyer, experienced landlord, home mover, looking to remortgage or to raise money for an extension, Oakdene Mortgages are here to help you every step of the way.
Protection
Protection
It is crucial to ensure that your family, home and loved ones are protected in the event of death, critical illness, accident & sickness.
Stay Connected
Figures from the ABI have highlighted the importance of protection cover, as insurers paid out £7.84bn in individual and group protection claims in 2025 - this is equivalent to £21.5m every day. Individual policies The research found that 97.9% of individual claims resulted in a payout last year. It has remained at or above this level for the last decade, meaning that the vast majority of individual protection claims resulted in a payout. Insurers paid out £5.15bn in individual life insurance, income protection and critical illness claims, which is 3% lower than in 2024 but 22% higher than in 2022. The average payout was £19,300 last year, up 2% on 2024. Work absences on the rise A recent survey by WTW shows that employee absence has reached the highest level in a decade in the UK. Half (51%) of UK employers have reported a rise in short-term absence over the last two years, while 55% noted an increase in long-term absence and disability. Mental health and workplace stress remain major concerns, alongside musculoskeletal (MSK) issues and chronic conditions. These findings tie in with the stats from the Association of British Insurers (ABI), which show that MSK conditions are the most common reason for income protection claims. Claims for mental health Awareness about mental health is growing, which has likely contributed to more people feeling able to take time off work when they are unable to cope. Last year, insurers paid out £39m in income protection claims to support those with mental health conditions, accounting for 19% of all claims paid. The importance of income protection Last year, 7,600 people who had made an income protection claim were able to return to work with the support of their payouts and other health services provided by their insurer. Meanwhile, more employers are recognising the importance of group protection policies, providing their employees with financial support if they are unable to work. Some of these group policies also provide rehabilitation support, helping employees return to work safely. Protection is invaluable Rebecca Ward, Assistant Director, Head of Health and Protection at the ABI emphasised the value of protection cover: “Protection insurance remains a cornerstone of financial resilience, helping customers and their loved ones navigate life’s most difficult moments. Each year, income protection, critical illness and life insurance policies provide vital financial support to thousands of people facing bereavement, illness or injury.” Here to help Our experts can ensure you and your family are adequately protected – contact us for advice today. As with all insurance policies, conditions and exclusions will apply Sources: https://www.abi.org.uk/media-hub/news-post/protection-insurers-pay-out-7-84-billion-to-help-customers-safeguard-their-finances https://www.wtwco.com/en-gb/insights/2026/04/optimising-absence-management-in-the-uk-the-role-of-group-income-protection Photo by Kelly Sikkema on Unsplash.
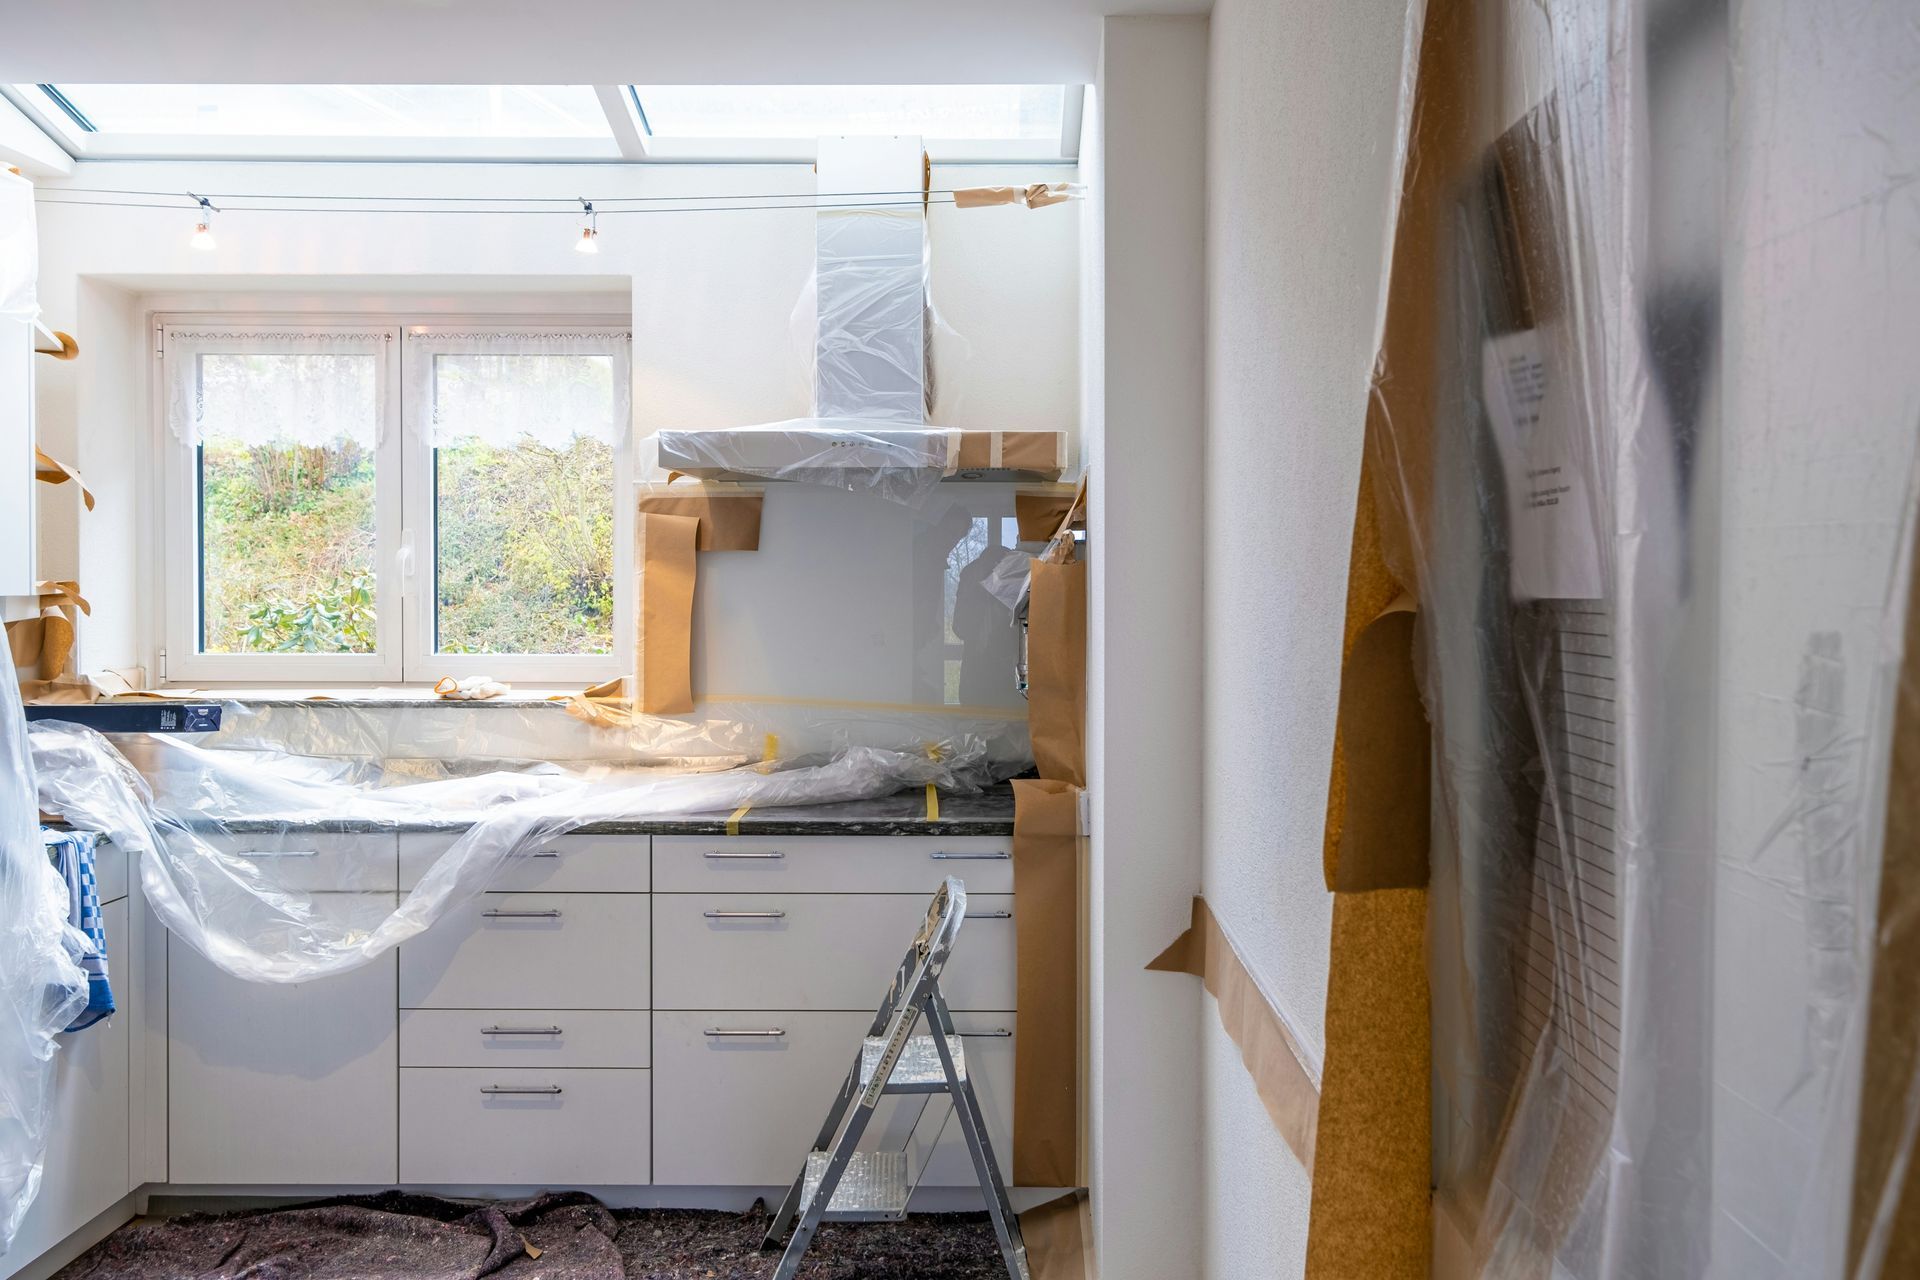
Making home renovations won’t always increase the value of your home, according to Rightmove. The research suggests that home improvements that don’t necessarily attract buyers. Sellers may be tempted to build an extension to make the property bigger, but this could be at the expense of garden or garage space. Similarly, if you’re spending money on a new kitchen, make sure to keep the design neutral as extravagant decoration could put off buyers. Think carefully before converting a bedroom into a specialist room, such as a cinema suite or walk-in wardrobe as not everyone wants these. If you’re looking to secure a sale, estate agents recommend focusing on the presentation and upkeep of your home before you invest in big upgrades. Sources: https://www.rightmove.co.uk/news/articles/property-news/5-renovations-sellers-think-add-value/ Photo by immo RENOVATION on Unsplash.
Analysis has found that there has been an increase in online searches related to income protection. According to the research, searches for ‘emergency savings’ increased annually by 950%. Meanwhile, enquiries about ‘financial protection’ rose by 130% and interest in ‘income protection’ went up by 30%. The increase in searches suggests growing interest in how households could manage financially if their income stopped. Despite this, only 9% of UK adults have income protection in place. The reality It’s easy to think that you won’t ever need to rely on income protection cover. However, 18% of adults took at least four weeks off work in the six months to March 2026, either because of illness, injury or mental health reasons. Nearly a quarter (23%) of this group relied on personal savings to support themselves, while 9% used a credit card or personal loan. Relying on savings or borrowing could reduce your financial buffer, particularly if an absence from work continues. Talk to us Income protection is there to provide financial support if you can no longer work due to illness or injury. If you’re worried about what would happen if your income stopped, talk to us. As with all insurance policies, conditions and exclusions will apply. Sources https://mortgagesoup.co.uk/emergency-savings-searches-surge-as-households-face-income-pressures/ Photo by Vitaly Gariev on Unsplash.
If you are a prospective first-time buyer (FTB), you may have considered low or no-deposit mortgages to help you get on the property ladder. However, these are complex loans, so it is important to be fully informed before making a decision. The government has also recently announced a new FTB initiative, called Your First Home, which is expected to support eligible buyers with smaller deposits through a government-backed equity loan. As with any homebuying scheme, it is important to understand the eligibility criteria, costs and long-term implications before proceeding. Things to consider Higher loan-to-value (LTV) mortgages can come with higher interest rates than some lower-LTV alternatives, although this varies between lenders and products. Lower rates are available with a 5% or 10% deposit – your mortgage adviser can assess whether it’s advisable to save for a for a little longer so you can increase your deposit and access better deals. With such a high LTV ratio, you would be at greater risk of falling into negative equity – this is when the amount you owe your mortgage lender is more than the value of your property. Even if you have a low deposit, you will likely still need to pay a substantial sum of money upfront. You should factor in Stamp Duty, conveyancing fees, surveys, moving costs and other unforeseen expenses. You will therefore still need to prepare your finances to afford this. No deposit deals If you have a 100% LTV (with no deposit), you could consider guarantor or family-assisted mortgages. A guarantor mortgage is when a relative or close friend may become responsible for some or all of the mortgage debt if the borrower cannot meet their obligations. The guarantor does not have a share in the property, but their own home would be at risk if they cannot repay the loan either. The details of family-assisted mortgage vary depending on the lender. It can involve a relative putting a set amount of savings into an account linked to the mortgage - this acts as security on the mortgage, which is released back to the family member after a specific length of time. What are the limitations? Making overpayments would help you to pay off your mortgage quicker, if you are in a better financial position in future. Lenders generally have a limit on how much you can overpay and there may be repayment charges, so check the terms. Some low-deposit deals do not include certain new-build homes or they have a limit on the property’s value. This may affect your ability to buy your ideal home, so consider if it is worth the compromise. Seek advice Don’t jump into anything - talk to us first. Your home may be repossessed if you do not keep up repayments on your mortgage Sources: https://www.gov.uk/first-homes-scheme https://www.whatmortgage.co.uk/news/no-deposit-mortgages-5-things-ftbs-should-watch-out-for/ Photo by Jakub Żerdzick on Unsplash
Whether you’re going on holiday or just heading out for the day, there are steps you can take to help protect your home from burglars. Between March 2024 and 2025, 245,284 burglaries were reported in England and Wales. With the nights getting longer, there are more opportunities for thieves to attempt a break-in under cover of darkness. While you cannot completely eliminate the risk of a burglary, there are precautionary measures to deter opportunistic burglars. Make use of technology Smart video doorbells have become increasingly popular – they allow you to keep an eye on activity outside your home when you aren’t in. Motion detection sensors that will send a notification to your phone when movement has occurred. Not only does this allow you to speak to a delivery driver while you’re away from home, it also helps you to spot any suspicious activity. Smart lightbulbs can also be useful, particularly if you’re going away. They can be controlled remotely from your phone and scheduled to switch on and off at different times, helping to create the impression that someone is at home, even when the property is empty. While the latest gadgets can be beneficial, it’s important not to overlook more traditional security measures. Check that your burglar alarm is working properly and get into the habit of setting it every time you leave the house. No empty driveways If you’re going away for an extended period, try to have a car parked outside your house - perhaps a friend or neighbour can help by using your driveway. They could also move your bins on the relevant days, so it is less obvious that the property is empty. Don’t attract attention Take a look at your home from the outside and check if any valuable items are visible through the windows. Laptops, televisions, game consoles and other expensive gadgets could attract the attention of a potential thief, so consider moving them out of sight. You should also lock away any ladders or tools that a burglar could use to gain access to your property. Before going away, check that all windows and doors are securely locked and avoid leaving spare keys in obvious hiding places, such as under a doormat or plant pot. Check your insurance If you are unlucky enough to experience a burglary, having the right cover will be essential. Buildings insurance will typically cover any insured damage to the structure of your home, such as broken glass and damaged locks. Contents insurance usually covers you for any possessions that have been stolen, subject to the policy terms, limits and exclusions. You may need additional cover for high-value items or bicycles, so it’s important to check the terms and conditions. Contact us to review your policy. As with all insurance policies, conditions and exclusions will apply. Sources: https://www.which.co.uk/news/article/10-tips-to-keep-your-home-safe-while-you-are-away-aF8t63i4fRA9 https://www.ons.gov.uk/peoplepopulationandcommunity/crimeandjustice/bulletins/crimeinenglandandwales/yearendingmarch2025?utm_source=chatgpt.com Photo by Sarah Brown on Unsplash Photo by Sarah Brown
on Unsplash
Research suggests that many buyers’ priorities have shifted, as they no longer look for properties requiring major renovation. A survey found that 53% of buyers would not take on a property that needed major work. Meanwhile, only 6% said they would actively look for a property that needs renovation. Some (41%) buyers were willing to consider taking on a project, provided that the asking price was reflective of the work that was required. First-time buyers (FTBs) have traditionally been attracted to fixer-upper properties because they offer a way to buy in a preferred location at a lower price. According to Nationwide, this is because it can enable new homeowners to buy in their preferred location and shape the home to their own taste. However, the survey by LRG indicates that FTB behaviour is changing, with only 5% saying they would seek out a home that needs renovating. The typical renovation project costs £85,000 or more, with 75% of FTBs carrying out more DIY on their new home than expected. The findings suggest that buyers may still be willing to renovate but are increasingly looking for the purchase price to reflect the cost and effort involved. We can help you – get in touch for mortgage advice. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://thenegotiator.co.uk/news/uk-housing-market-news/no-desire-for-doer-uppers-as-buyers-seek-certainty/ https://thepropertyai.co.uk/property-news/buyers-turn-away-from-renovation-projects-lrg-survey-finds?utm_source=chatgpt.com Photo by Roselyn Tirado on Unsplash Photo by Roselyn Tirado
on Unsplash
Contact us
Business Hours
- Mon - Fri
- -
- Saturday
- Appointment only
- Sunday
- Closed
Address
41 Oakdene Crescent, Portslade, Brighton, BN41 2RP, United Kingdom
