
WHOLE OF MARKET MORTGAGE ADVICE
Buying - Remortgage
Further Borrowing - Buy to Let
Insurance - Protection
Whole of Market Mortgage Advice
Oakdene Mortgages are independent, whole-of-market mortgage and protection brokers serving clients In Brighton & Hove, East & West Sussex and across the UK. We’re proud to have built a reputation for excellent service, with 5-star reviews from clients who value our approachable style and expert knowledge. From first-time buyers navigating their first purchase to landlords building their portfolio, we combine experience with genuine care to ensure you feel confident and supported throughout the process. All with no Broker Fees
MORTGAGES
MORTGAGES
Whether you are a first time buyer, experienced landlord, home mover, looking to remortgage or to raise money for an extension, Oakdene Mortgages are here to help you every step of the way.
Protection
Protection
It is crucial to ensure that your family, home and loved ones are protected in the event of death, critical illness, accident & sickness.
Stay Connected
Research has found that many parents with children under 18 do not have appropriate protection in place, potentially leaving their families vulnerable to financial shocks. The survey indicates that many parents would struggle to maintain their current standard of living if they were unable to work due to illness or injury. A third (32%) said they could cover essential expenses for less than three months if their income stopped. Meanwhile, if they were out of work for a year, the biggest concern for parents would be paying their household bills (50%) and keeping up with mortgage or rent payments (49%). Almost half (46%) were worried about being able to afford food and other necessities. Parents putting it off Four in ten parents expressed concern about providing for their family if their income stopped. This anxiety could be alleviated by taking out protection, which provides peace of mind that you will be covered through life’s unexpected moments. However, many survey respondents did not have adequate insurance in place. Over a third (37%) said they thought about getting income protection when they had children, but only 18% actually did so. This suggests that, while some parents understand the value of protection, it is not the top of their priority list. Justin Garbutt at Vitality commented, "There is a clear gap between how much parents value protection and how often it gets acted on. Many recognise its importance, but good intentions are not always translating into action.” Are your savings enough? It may be tempting to rely on your savings instead of a protection policy, but have you worked out how long these funds would realistically last? Nearly a third (31%) of respondents said they have less than £3,000 to fall back on if their income stopped. For most families, this would not be a sufficient financial buffer, so an additional layer of support would be necessary. Consult an adviser According to the survey, 13% of parents said that they would like to get protection, but they haven’t got round to it yet. Meanwhile, 31% are concerned that they can’t afford protection. A professional adviser can support you through the process and source a policy that works for your financial situation. We understand that when you’re a parent, there are lots of tasks on your to-do list, but protection is not something that should be overlooked. Making time to sort this now could significantly alleviate stress in the future, should you be unable to work. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://protectionreporter.co.uk/one-in-three-parents-lack-protection-for-income-shock.html https://www.vitality.co.uk/media/new-research-suggests-income-shock-could-push-one-in-three-parents-into-hardship-within-three-months/ Photo by Lawrence Crayton on Unsplash Photo by Lawrence Crayton
on Unsplash
Recent data has emphasised the importance of being transparent with your insurer, otherwise your protection claim could be denied. According to LV=, around 5% of protection claims were declined in 2025. The main reasons for this were misrepresentation or non-disclosure; policyholders commonly provided inaccurate information about their smoking status, alcohol consumption and medical history. Leaving out a detail or telling a small ‘white lie’ when applying for protection insurance may seem insignificant. However, even minor inaccuracies could affect the validity of your cover and ultimately prevent you from receiving a payout when you need it most. We understand that non-disclosure might not always be intentional. You may simply forget to mention a previous medical condition, particularly if it happened a long time ago. This is why it is important to take your time when completing an application and check your records carefully. Don’t let inaccuracies be the reason you don’t receive a payout. If you already have protection in place, it is worth checking that the information you provided when applying is accurate and your insurer has been informed of any changes in circumstances. As with all insurance policies, conditions and exclusions will apply. Sources: https://www.covermagazine.co.uk/news/4532874/misrepresentation-disclosure-reasons-denied-claims-lv https://www.lv.com/about-us/press/lv-pays-out-nearly-152-million-in-protection-claims-in-2025-its-highest-on-record?utm Photo by Vitaly Gariev on Unsplash Photo by Vitaly Gariev
on Unsplash
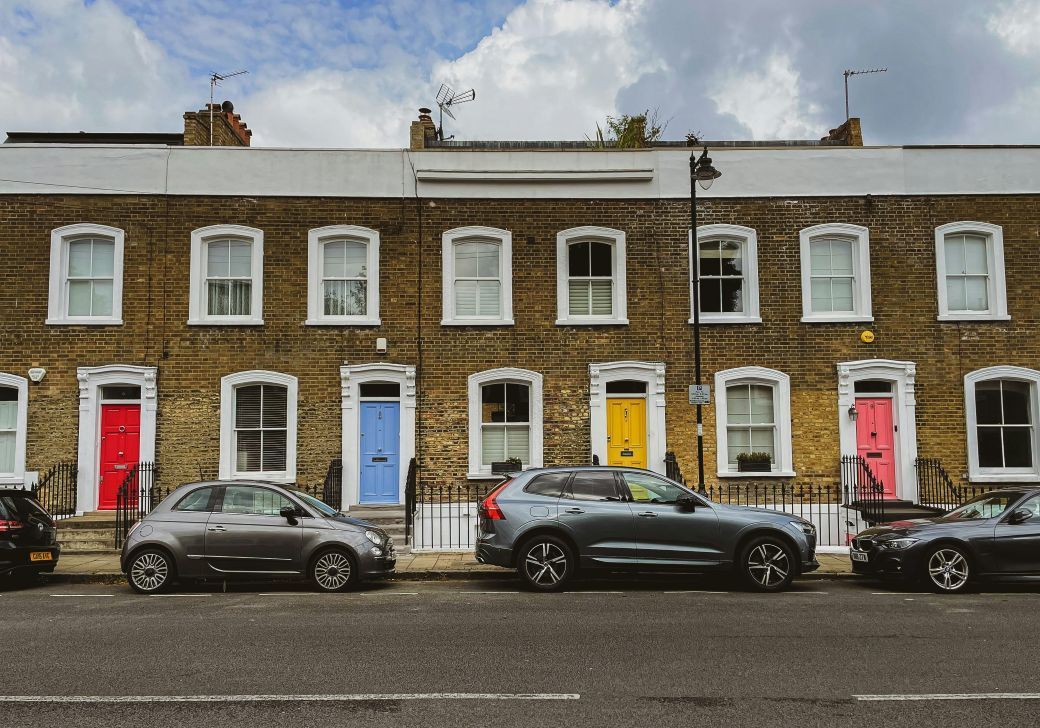
Flats are the best value they have been in 30 years, according to Zoopla. The typical flat is currently 40% cheaper than a house, marking the widest price gap since records began. Since 2017, the price of a flat has risen by just over 10%, while the average house price has gone up by 43% over the same period. The average house costs 1.7 times more than a flat, but this ratio varies depending on the region. The biggest price gap is seen in the West Midlands, where the house-flat ratio is 2.5. Meanwhile, in London, the ratio is lower at 1.9 where property prices are higher overall. However, these figures do not take into account the additional charges payable on a leasehold flat. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.zoopla.co.uk/discover/property-news/flats-are-40-cheaper-to-buy-than-houses-the-best-value-for-30-years/ Photo by Marlene Celine Nordvik from Unsplash Photo by Marlene Céline Nordvik
on Unsplash
Thinking of putting your house on the market? Getting the asking price right is essential to attracting a buyer. Here are some things to consider. Market update It was a slow summer for the housing market, as affordability pressures took their toll on buyer confidence. The number of sales agreed fell annually by 9% in July, according to Zoopla. This is likely due to raised mortgage rates, which have added about £125 to monthly repayments for the typical buyer. Although the short-term outlook is uncertain, there is hope for sellers, as homes that are priced appropriately still have a chance of getting a buyer. A buyer’s market Buyers currently have a lot of choice; the number of available homes increased in eight out of 11 regions when compared with last year. This has given buyers greater negotiating power, so sellers need to price competitively. Common pitfalls In current market conditions, it is risky to be overly ambitious with your pricing. You should therefore do your market research and decide a price based on recent sold prices, rather than focusing on advertised asking prices. It may be tempting to go for a high asking price knowing that you can adjust it later. But this approach will likely take you longer to sell. In July, 30% of homes that had been on the market since quarter two were still unsold, without any price reduction. But research from Savills shows that a seller who gets the price right from the outset can achieve an agreed sale within 28 days. However, if there is one price cut, it could take over three months to receive an offer. This time could extend to nearly five and a half months if there are two price adjustments. Know your area While it’s useful to know what is going on in national markets, it’s essential to understand the conditions in your area. 76% of local markets recorded a fall in agreed sales between May and July; however, about a quarter of areas saw stable or increasing activity during that time. For example, Warrington, Hull and Dundee have experienced strong house price growth and a rise in sales. Meanwhile, Bath, Oxford and Harrow have recorded a slowdown in sales and weakening price growth. You should therefore speak to a few local estate agents to get their advice on a reasonable price for your property type in your own area. Seek advice If you’re looking to move home this autumn, get in touch with us. We can help you ascertain what you can reasonably afford, so you can enter your property search in the best possible position. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.zoopla.co.uk/discover/property-news/is-now-a-good-time-to-sell-your-house-heres-what-really-matters-in-2026/ https://www.zoopla.co.uk/discover/property-news/house-price-index/ https://www.ft.com/content/24a8adf9-8103-44b3-92e8-350ef897dc2a?syn-25a6b1a6=1 Photo by Daniil Korbut on Unsplash Photo by Daniil Korbut
on Unsplash

Applications for the Scottish Government’s First Homes Fund are now open, providing first-time buyers (FTBs) with up to £10,000 towards a deposit. The First Homes Fund is a shared-equity scheme open to any prospective new homeowners in Scotland. The fund can be used to purchase any home (whether new build or existing property) valued up to £300,000. It is part of the Scottish Government’s plans to support 50,000 households over the course of this Parliament. This first phase of the fund is set to help 2,000 FTBs get on the property ladder by September. If you buy using the First Homes Fund, the Scottish Government will own a share of your property. However, you would still own the home and hold the title to it. To protect the Government's share, you must have a mortgage covering at least 25% of the purchase price. The Government's share is usually repaid when the property is sold. You must have had an offer accepted on a home before applying for the First Homes Fund. However, it's worth discussing your options beforehand. Contact us if you would like to find out more. We can answer your questions and help you decide whether the scheme is right for you. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.gov.scot/news/first-homes-fund-open-by-end-of-june/ https://www.mygov.scot/first-homes-fund/before-you-apply

If you’re busy looking after your children, you may not have had a chance to stop and think about life insurance, but this is key to protecting your family’s future. We know it’s not easy to think about what would happen in the event of your death; however, the loss of your income could significantly impact your family’s lifestyle at an already distressing time. Even if you are a stay-at-home parent, it could cost a lot to replace what you contribute to the household in childcare. The benefits for your children Attending higher education often comes at a great cost for a child and their families. With the right protection policy, you can ensure that your offspring would still have the opportunity to attend university or training, even if you are not there to support them. There are different types of life insurance to choose from depending on your needs. Family income benefit is designed to provide regular monthly payments to surviving family members, rather than a lump sum. This can help give you peace of mind that your loved ones would still receive a steady income if you passed away. The earlier you take steps to secure a happy financial future for your kids, the better - review your policy now. As with all insurance policies, conditions and exclusions will apply Sources: https://www.zurich.co.uk/life-insurance/start-protecting-your-childs-future https://go2-mortgages.co.uk/blog/securing-your-childs-future-the-role-of-life-insurance-in-long-term-planning
Contact us
Business Hours
- Mon - Fri
- -
- Saturday
- Appointment only
- Sunday
- Closed
Address
41 Oakdene Crescent, Portslade, Brighton, BN41 2RP, United Kingdom
