BLOGS
BLOGS
Figures from the ABI have highlighted the importance of protection cover, as insurers paid out £7.84bn in individual and group protection claims in 2025 - this is equivalent to £21.5m every day. Individual policies The research found that 97.9% of individual claims resulted in a payout last year. It has remained at or above this level for the last decade, meaning that the vast majority of individual protection claims resulted in a payout. Insurers paid out £5.15bn in individual life insurance, income protection and critical illness claims, which is 3% lower than in 2024 but 22% higher than in 2022. The average payout was £19,300 last year, up 2% on 2024. Work absences on the rise A recent survey by WTW shows that employee absence has reached the highest level in a decade in the UK. Half (51%) of UK employers have reported a rise in short-term absence over the last two years, while 55% noted an increase in long-term absence and disability. Mental health and workplace stress remain major concerns, alongside musculoskeletal (MSK) issues and chronic conditions. These findings tie in with the stats from the Association of British Insurers (ABI), which show that MSK conditions are the most common reason for income protection claims. Claims for mental health Awareness about mental health is growing, which has likely contributed to more people feeling able to take time off work when they are unable to cope. Last year, insurers paid out £39m in income protection claims to support those with mental health conditions, accounting for 19% of all claims paid. The importance of income protection Last year, 7,600 people who had made an income protection claim were able to return to work with the support of their payouts and other health services provided by their insurer. Meanwhile, more employers are recognising the importance of group protection policies, providing their employees with financial support if they are unable to work. Some of these group policies also provide rehabilitation support, helping employees return to work safely. Protection is invaluable Rebecca Ward, Assistant Director, Head of Health and Protection at the ABI emphasised the value of protection cover: “Protection insurance remains a cornerstone of financial resilience, helping customers and their loved ones navigate life’s most difficult moments. Each year, income protection, critical illness and life insurance policies provide vital financial support to thousands of people facing bereavement, illness or injury.” Here to help Our experts can ensure you and your family are adequately protected – contact us for advice today. As with all insurance policies, conditions and exclusions will apply Sources: https://www.abi.org.uk/media-hub/news-post/protection-insurers-pay-out-7-84-billion-to-help-customers-safeguard-their-finances https://www.wtwco.com/en-gb/insights/2026/04/optimising-absence-management-in-the-uk-the-role-of-group-income-protection Photo by Kelly Sikkema on Unsplash.
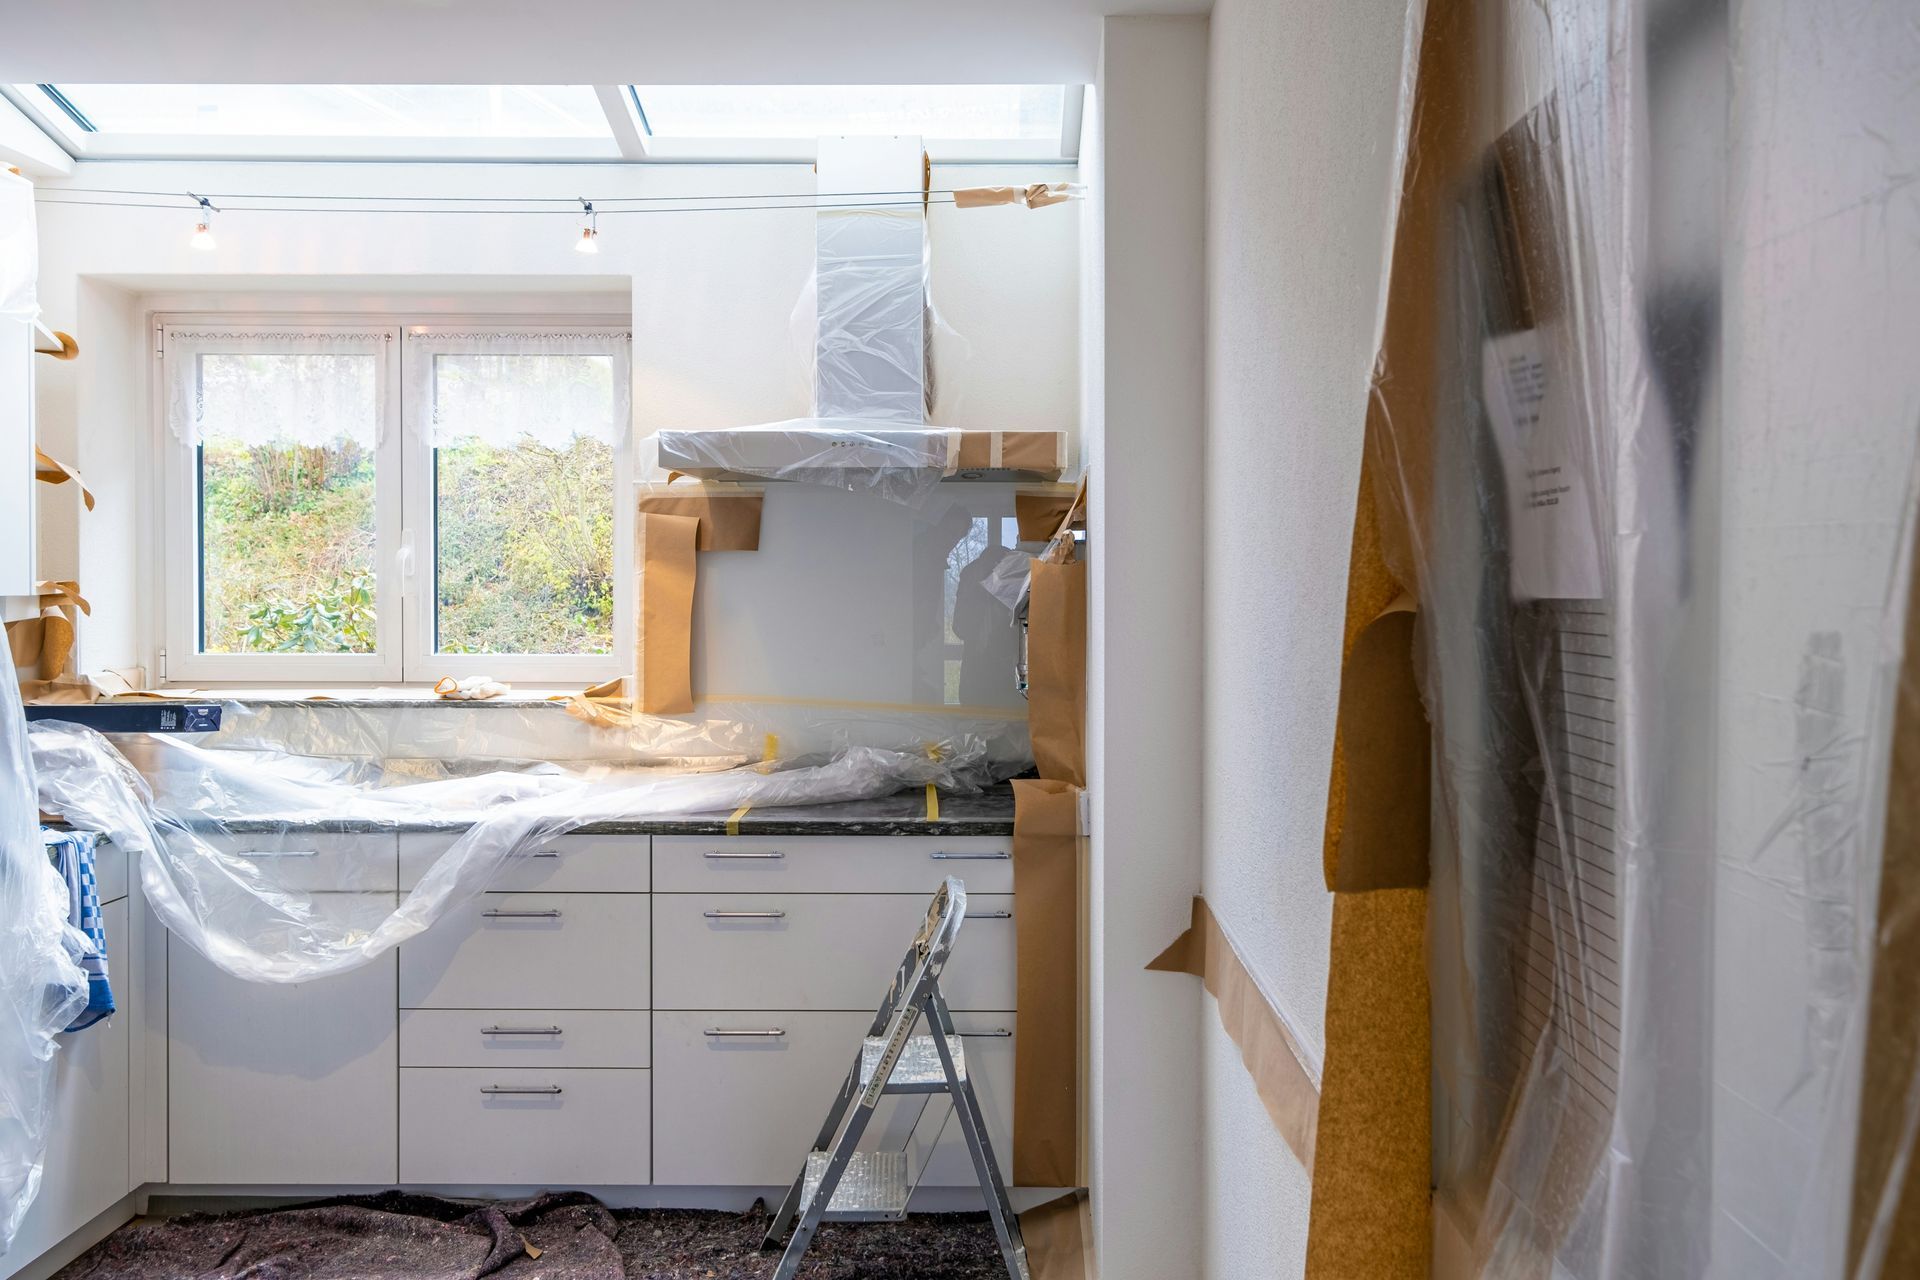
Making home renovations won’t always increase the value of your home, according to Rightmove. The research suggests that home improvements that don’t necessarily attract buyers. Sellers may be tempted to build an extension to make the property bigger, but this could be at the expense of garden or garage space. Similarly, if you’re spending money on a new kitchen, make sure to keep the design neutral as extravagant decoration could put off buyers. Think carefully before converting a bedroom into a specialist room, such as a cinema suite or walk-in wardrobe as not everyone wants these. If you’re looking to secure a sale, estate agents recommend focusing on the presentation and upkeep of your home before you invest in big upgrades. Sources: https://www.rightmove.co.uk/news/articles/property-news/5-renovations-sellers-think-add-value/ Photo by immo RENOVATION on Unsplash.
Analysis has found that there has been an increase in online searches related to income protection. According to the research, searches for ‘emergency savings’ increased annually by 950%. Meanwhile, enquiries about ‘financial protection’ rose by 130% and interest in ‘income protection’ went up by 30%. The increase in searches suggests growing interest in how households could manage financially if their income stopped. Despite this, only 9% of UK adults have income protection in place. The reality It’s easy to think that you won’t ever need to rely on income protection cover. However, 18% of adults took at least four weeks off work in the six months to March 2026, either because of illness, injury or mental health reasons. Nearly a quarter (23%) of this group relied on personal savings to support themselves, while 9% used a credit card or personal loan. Relying on savings or borrowing could reduce your financial buffer, particularly if an absence from work continues. Talk to us Income protection is there to provide financial support if you can no longer work due to illness or injury. If you’re worried about what would happen if your income stopped, talk to us. As with all insurance policies, conditions and exclusions will apply. Sources https://mortgagesoup.co.uk/emergency-savings-searches-surge-as-households-face-income-pressures/ Photo by Vitaly Gariev on Unsplash.
If you are a prospective first-time buyer (FTB), you may have considered low or no-deposit mortgages to help you get on the property ladder. However, these are complex loans, so it is important to be fully informed before making a decision. The government has also recently announced a new FTB initiative, called Your First Home, which is expected to support eligible buyers with smaller deposits through a government-backed equity loan. As with any homebuying scheme, it is important to understand the eligibility criteria, costs and long-term implications before proceeding. Things to consider Higher loan-to-value (LTV) mortgages can come with higher interest rates than some lower-LTV alternatives, although this varies between lenders and products. Lower rates are available with a 5% or 10% deposit – your mortgage adviser can assess whether it’s advisable to save for a for a little longer so you can increase your deposit and access better deals. With such a high LTV ratio, you would be at greater risk of falling into negative equity – this is when the amount you owe your mortgage lender is more than the value of your property. Even if you have a low deposit, you will likely still need to pay a substantial sum of money upfront. You should factor in Stamp Duty, conveyancing fees, surveys, moving costs and other unforeseen expenses. You will therefore still need to prepare your finances to afford this. No deposit deals If you have a 100% LTV (with no deposit), you could consider guarantor or family-assisted mortgages. A guarantor mortgage is when a relative or close friend may become responsible for some or all of the mortgage debt if the borrower cannot meet their obligations. The guarantor does not have a share in the property, but their own home would be at risk if they cannot repay the loan either. The details of family-assisted mortgage vary depending on the lender. It can involve a relative putting a set amount of savings into an account linked to the mortgage - this acts as security on the mortgage, which is released back to the family member after a specific length of time. What are the limitations? Making overpayments would help you to pay off your mortgage quicker, if you are in a better financial position in future. Lenders generally have a limit on how much you can overpay and there may be repayment charges, so check the terms. Some low-deposit deals do not include certain new-build homes or they have a limit on the property’s value. This may affect your ability to buy your ideal home, so consider if it is worth the compromise. Seek advice Don’t jump into anything - talk to us first. Your home may be repossessed if you do not keep up repayments on your mortgage Sources: https://www.gov.uk/first-homes-scheme https://www.whatmortgage.co.uk/news/no-deposit-mortgages-5-things-ftbs-should-watch-out-for/ Photo by Jakub Żerdzick on Unsplash
Whether you’re going on holiday or just heading out for the day, there are steps you can take to help protect your home from burglars. Between March 2024 and 2025, 245,284 burglaries were reported in England and Wales. With the nights getting longer, there are more opportunities for thieves to attempt a break-in under cover of darkness. While you cannot completely eliminate the risk of a burglary, there are precautionary measures to deter opportunistic burglars. Make use of technology Smart video doorbells have become increasingly popular – they allow you to keep an eye on activity outside your home when you aren’t in. Motion detection sensors that will send a notification to your phone when movement has occurred. Not only does this allow you to speak to a delivery driver while you’re away from home, it also helps you to spot any suspicious activity. Smart lightbulbs can also be useful, particularly if you’re going away. They can be controlled remotely from your phone and scheduled to switch on and off at different times, helping to create the impression that someone is at home, even when the property is empty. While the latest gadgets can be beneficial, it’s important not to overlook more traditional security measures. Check that your burglar alarm is working properly and get into the habit of setting it every time you leave the house. No empty driveways If you’re going away for an extended period, try to have a car parked outside your house - perhaps a friend or neighbour can help by using your driveway. They could also move your bins on the relevant days, so it is less obvious that the property is empty. Don’t attract attention Take a look at your home from the outside and check if any valuable items are visible through the windows. Laptops, televisions, game consoles and other expensive gadgets could attract the attention of a potential thief, so consider moving them out of sight. You should also lock away any ladders or tools that a burglar could use to gain access to your property. Before going away, check that all windows and doors are securely locked and avoid leaving spare keys in obvious hiding places, such as under a doormat or plant pot. Check your insurance If you are unlucky enough to experience a burglary, having the right cover will be essential. Buildings insurance will typically cover any insured damage to the structure of your home, such as broken glass and damaged locks. Contents insurance usually covers you for any possessions that have been stolen, subject to the policy terms, limits and exclusions. You may need additional cover for high-value items or bicycles, so it’s important to check the terms and conditions. Contact us to review your policy. As with all insurance policies, conditions and exclusions will apply. Sources: https://www.which.co.uk/news/article/10-tips-to-keep-your-home-safe-while-you-are-away-aF8t63i4fRA9 https://www.ons.gov.uk/peoplepopulationandcommunity/crimeandjustice/bulletins/crimeinenglandandwales/yearendingmarch2025?utm_source=chatgpt.com Photo by Sarah Brown on Unsplash Photo by Sarah Brown
on Unsplash
Research suggests that many buyers’ priorities have shifted, as they no longer look for properties requiring major renovation. A survey found that 53% of buyers would not take on a property that needed major work. Meanwhile, only 6% said they would actively look for a property that needs renovation. Some (41%) buyers were willing to consider taking on a project, provided that the asking price was reflective of the work that was required. First-time buyers (FTBs) have traditionally been attracted to fixer-upper properties because they offer a way to buy in a preferred location at a lower price. According to Nationwide, this is because it can enable new homeowners to buy in their preferred location and shape the home to their own taste. However, the survey by LRG indicates that FTB behaviour is changing, with only 5% saying they would seek out a home that needs renovating. The typical renovation project costs £85,000 or more, with 75% of FTBs carrying out more DIY on their new home than expected. The findings suggest that buyers may still be willing to renovate but are increasingly looking for the purchase price to reflect the cost and effort involved. We can help you – get in touch for mortgage advice. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://thenegotiator.co.uk/news/uk-housing-market-news/no-desire-for-doer-uppers-as-buyers-seek-certainty/ https://thepropertyai.co.uk/property-news/buyers-turn-away-from-renovation-projects-lrg-survey-finds?utm_source=chatgpt.com Photo by Roselyn Tirado on Unsplash Photo by Roselyn Tirado
on Unsplash
Research has found that many parents with children under 18 do not have appropriate protection in place, potentially leaving their families vulnerable to financial shocks. The survey indicates that many parents would struggle to maintain their current standard of living if they were unable to work due to illness or injury. A third (32%) said they could cover essential expenses for less than three months if their income stopped. Meanwhile, if they were out of work for a year, the biggest concern for parents would be paying their household bills (50%) and keeping up with mortgage or rent payments (49%). Almost half (46%) were worried about being able to afford food and other necessities. Parents putting it off Four in ten parents expressed concern about providing for their family if their income stopped. This anxiety could be alleviated by taking out protection, which provides peace of mind that you will be covered through life’s unexpected moments. However, many survey respondents did not have adequate insurance in place. Over a third (37%) said they thought about getting income protection when they had children, but only 18% actually did so. This suggests that, while some parents understand the value of protection, it is not the top of their priority list. Justin Garbutt at Vitality commented, "There is a clear gap between how much parents value protection and how often it gets acted on. Many recognise its importance, but good intentions are not always translating into action.” Are your savings enough? It may be tempting to rely on your savings instead of a protection policy, but have you worked out how long these funds would realistically last? Nearly a third (31%) of respondents said they have less than £3,000 to fall back on if their income stopped. For most families, this would not be a sufficient financial buffer, so an additional layer of support would be necessary. Consult an adviser According to the survey, 13% of parents said that they would like to get protection, but they haven’t got round to it yet. Meanwhile, 31% are concerned that they can’t afford protection. A professional adviser can support you through the process and source a policy that works for your financial situation. We understand that when you’re a parent, there are lots of tasks on your to-do list, but protection is not something that should be overlooked. Making time to sort this now could significantly alleviate stress in the future, should you be unable to work. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://protectionreporter.co.uk/one-in-three-parents-lack-protection-for-income-shock.html https://www.vitality.co.uk/media/new-research-suggests-income-shock-could-push-one-in-three-parents-into-hardship-within-three-months/ Photo by Lawrence Crayton on Unsplash Photo by Lawrence Crayton
on Unsplash
Recent data has emphasised the importance of being transparent with your insurer, otherwise your protection claim could be denied. According to LV=, around 5% of protection claims were declined in 2025. The main reasons for this were misrepresentation or non-disclosure; policyholders commonly provided inaccurate information about their smoking status, alcohol consumption and medical history. Leaving out a detail or telling a small ‘white lie’ when applying for protection insurance may seem insignificant. However, even minor inaccuracies could affect the validity of your cover and ultimately prevent you from receiving a payout when you need it most. We understand that non-disclosure might not always be intentional. You may simply forget to mention a previous medical condition, particularly if it happened a long time ago. This is why it is important to take your time when completing an application and check your records carefully. Don’t let inaccuracies be the reason you don’t receive a payout. If you already have protection in place, it is worth checking that the information you provided when applying is accurate and your insurer has been informed of any changes in circumstances. As with all insurance policies, conditions and exclusions will apply. Sources: https://www.covermagazine.co.uk/news/4532874/misrepresentation-disclosure-reasons-denied-claims-lv https://www.lv.com/about-us/press/lv-pays-out-nearly-152-million-in-protection-claims-in-2025-its-highest-on-record?utm Photo by Vitaly Gariev on Unsplash Photo by Vitaly Gariev
on Unsplash
Flats are the best value they have been in 30 years, according to Zoopla. The typical flat is currently 40% cheaper than a house, marking the widest price gap since records began. Since 2017, the price of a flat has risen by just over 10%, while the average house price has gone up by 43% over the same period. The average house costs 1.7 times more than a flat, but this ratio varies depending on the region. The biggest price gap is seen in the West Midlands, where the house-flat ratio is 2.5. Meanwhile, in London, the ratio is lower at 1.9 where property prices are higher overall. However, these figures do not take into account the additional charges payable on a leasehold flat. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.zoopla.co.uk/discover/property-news/flats-are-40-cheaper-to-buy-than-houses-the-best-value-for-30-years/ Photo by Marlene Celine Nordvik from Unsplash Photo by Marlene Céline Nordvik
on Unsplash
Thinking of putting your house on the market? Getting the asking price right is essential to attracting a buyer. Here are some things to consider. Market update It was a slow summer for the housing market, as affordability pressures took their toll on buyer confidence. The number of sales agreed fell annually by 9% in July, according to Zoopla. This is likely due to raised mortgage rates, which have added about £125 to monthly repayments for the typical buyer. Although the short-term outlook is uncertain, there is hope for sellers, as homes that are priced appropriately still have a chance of getting a buyer. A buyer’s market Buyers currently have a lot of choice; the number of available homes increased in eight out of 11 regions when compared with last year. This has given buyers greater negotiating power, so sellers need to price competitively. Common pitfalls In current market conditions, it is risky to be overly ambitious with your pricing. You should therefore do your market research and decide a price based on recent sold prices, rather than focusing on advertised asking prices. It may be tempting to go for a high asking price knowing that you can adjust it later. But this approach will likely take you longer to sell. In July, 30% of homes that had been on the market since quarter two were still unsold, without any price reduction. But research from Savills shows that a seller who gets the price right from the outset can achieve an agreed sale within 28 days. However, if there is one price cut, it could take over three months to receive an offer. This time could extend to nearly five and a half months if there are two price adjustments. Know your area While it’s useful to know what is going on in national markets, it’s essential to understand the conditions in your area. 76% of local markets recorded a fall in agreed sales between May and July; however, about a quarter of areas saw stable or increasing activity during that time. For example, Warrington, Hull and Dundee have experienced strong house price growth and a rise in sales. Meanwhile, Bath, Oxford and Harrow have recorded a slowdown in sales and weakening price growth. You should therefore speak to a few local estate agents to get their advice on a reasonable price for your property type in your own area. Seek advice If you’re looking to move home this autumn, get in touch with us. We can help you ascertain what you can reasonably afford, so you can enter your property search in the best possible position. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.zoopla.co.uk/discover/property-news/is-now-a-good-time-to-sell-your-house-heres-what-really-matters-in-2026/ https://www.zoopla.co.uk/discover/property-news/house-price-index/ https://www.ft.com/content/24a8adf9-8103-44b3-92e8-350ef897dc2a?syn-25a6b1a6=1 Photo by Daniil Korbut on Unsplash Photo by Daniil Korbut
on Unsplash
Applications for the Scottish Government’s First Homes Fund are now open, providing first-time buyers (FTBs) with up to £10,000 towards a deposit. The First Homes Fund is a shared-equity scheme open to any prospective new homeowners in Scotland. The fund can be used to purchase any home (whether new build or existing property) valued up to £300,000. It is part of the Scottish Government’s plans to support 50,000 households over the course of this Parliament. This first phase of the fund is set to help 2,000 FTBs get on the property ladder by September. If you buy using the First Homes Fund, the Scottish Government will own a share of your property. However, you would still own the home and hold the title to it. To protect the Government's share, you must have a mortgage covering at least 25% of the purchase price. The Government's share is usually repaid when the property is sold. You must have had an offer accepted on a home before applying for the First Homes Fund. However, it's worth discussing your options beforehand. Contact us if you would like to find out more. We can answer your questions and help you decide whether the scheme is right for you. Your home may be repossessed if you do not keep up repayments on your mortgage. Sources: https://www.gov.scot/news/first-homes-fund-open-by-end-of-june/ https://www.mygov.scot/first-homes-fund/before-you-apply
If you’re busy looking after your children, you may not have had a chance to stop and think about life insurance, but this is key to protecting your family’s future. We know it’s not easy to think about what would happen in the event of your death; however, the loss of your income could significantly impact your family’s lifestyle at an already distressing time. Even if you are a stay-at-home parent, it could cost a lot to replace what you contribute to the household in childcare. The benefits for your children Attending higher education often comes at a great cost for a child and their families. With the right protection policy, you can ensure that your offspring would still have the opportunity to attend university or training, even if you are not there to support them. There are different types of life insurance to choose from depending on your needs. Family income benefit is designed to provide regular monthly payments to surviving family members, rather than a lump sum. This can help give you peace of mind that your loved ones would still receive a steady income if you passed away. The earlier you take steps to secure a happy financial future for your kids, the better - review your policy now. As with all insurance policies, conditions and exclusions will apply Sources: https://www.zurich.co.uk/life-insurance/start-protecting-your-childs-future https://go2-mortgages.co.uk/blog/securing-your-childs-future-the-role-of-life-insurance-in-long-term-planning
According to the Association of British Insurers, home insurers paid out a record amount for theft-related claims in the first quarter of 2026. The average sum paid out for a theft claim at the start of the year was £4,350, which is 14% higher than last year’s average. Meanwhile, separate data from the police force shows that garage thefts increased by 13% across Britain between 2022 and 2025. Two in five of these break-ins were preventable, as the door was left open at the time of the theft. It’s easy to get complacent and think it won’t happen to you, but these statistics highlight the importance of making sure your home is secure. Take the time to lock up your garage and outbuildings as they can be easy targets. As with all insurance policies, conditions and exclusions will apply Sources: https://www.thisismoney.co.uk/money/bills/article-15801151/Home-insurance-payouts-theft-hit-record-high-start-2026-spike-garage-break-ins-revealed.html https://www.thisismoney.co.uk/money/mortgageshome/article-15758603/Home-garage-thefts-rising-five-steps-turn-garage-fortress.html
Buying a home is an exciting prospect, but it can also come with stresses. From property hunting through to moving day, there is a lot to consider during the process. The impact on wellbeing According to research from Barratt Homes, 60% of UK homeowners said that the homebuying process took a toll on their mental wellbeing. An additional 35% experienced disrupted sleep, while 29% reported that their sense of financial security was impacted. The survey found that legal or conveyancing delays were the biggest source of stress, with 43% of respondents identifying this as a challenge. More than a third (37%) said that they were stressed due to a deal falling through or nearly falling through and 29% had challenges finding a suitable property. If you too are feeling stressed by the homebuying process, here are some top tips to help the journey feel more manageable. Expect the unexpected There is a lot of uncertainty that comes with buying a home - it can be hard to predict exactly when you will be able to move, particularly if you are part of a chain. It’s therefore advisable to expect delays so that you don’t feel disappointed if the legal process takes longer than anticipated. Try not to cut costs We understand that buying is a very expensive process. During this time, you might be cautious about your spending in other aspects of your life, so that you can save money where you can. However, it is important not to skip over certain parts of the homebuying process, as this could cost you more further down the line. For example, it may feel like getting a house survey is an avoidable expense, but this vital step highlights any issues with the property that could be costly to repair. Identifying these defects at an early stage may prompt you to renegotiate the purchase price, budget for repairs or even change your mind about buying the property. A step at a time It can be overwhelming to think about the whole homebuying process, so take it a step at a time rather than worrying about moving day before you’ve even placed an offer. That will allow you to focus on what you need to do right now, like attend a viewing or make a mortgage application. It can also help to store all important paperwork, emails and online documents in one place, so the information is easily accessible. Remember why you’re doing it If you’re ever feeling frustrated, remind yourself of the end result. Make sure to celebrate the small milestones, because each step takes you closer to collecting your keys and moving into your new home. You don’t have to navigate the homebuying process alone – we can help alleviate the stress and support you every step of the way. Your home may be repossessed if you do not keep up repayments on your mortgage Source: https://www.mpamag.com/uk/news/general/homebuying-takes-a-mental-toll-on-three-in-five-uk-buyers-research-finds/576591 https://www.barratthomes.co.uk/advice-and-inspiration/is-buying-a-home-stressful/
Analysis from Moneyfacts shows how borrowers’ priorities have shifted due to the economic impact of the Middle East conflict. Mortgage rates have been fluctuating since March and the short-term economic outlook is still unpredictable. As such, borrowers are increasingly looking for more flexible mortgage deals in the hope that rates will come down soon. According to the data, 6% of borrowers were looking for a variable or tracker deal last September, but this figure rose to 13% in April after the outbreak of war. Meanwhile, the share of mortgage holders looking for a two-year fixed deal increased from 49% to 53%. The statistics suggest that people are reluctant to commit to a five-year deal at the moment, as searches have gone down from 27% to 23%. Adam French at Moneyfacts said, “Demand for five-year fixes is usually strongest among homemovers, who value certainty in their monthly payments, particularly as they have usually taken on a larger debt. Instead, there has been a dramatic swing towards shorter term options.” We can help you navigate the changing mortgage market and find a deal that works for you and your finances. Get in touch for advice today. Your home may be repossessed if you do not keep up repayments on your mortgage Sources: https://www.mortgagestrategy.co.uk/news/demand-for-variable-rates-doubles-moneyfacts/ https://www.moneyfactsgroup.co.uk/media-centre/consumer/rocketing-rates-drive-borrowers-toward-two-year-fix-and-variable-deals/
Buying a home is an exciting prospect, but it can also come with stresses. From property hunting through to moving day, there is a lot to consider during the process. The impact on wellbeing According to research from Barratt Homes, 60% of UK homeowners said that the homebuying process took a toll on their mental wellbeing. An additional 35% experienced disrupted sleep, while 29% reported that their sense of financial security was impacted. The survey found that legal or conveyancing delays were the biggest source of stress, with 43% of respondents identifying this as a challenge. More than a third (37%) said that they were stressed due to a deal falling through or nearly falling through and 29% had challenges finding a suitable property. If you too are feeling stressed by the homebuying process, here are some top tips to help the journey feel more manageable. Expect the unexpected There is a lot of uncertainty that comes with buying a home - it can be hard to predict exactly when you will be able to move, particularly if you are part of a chain. It’s therefore advisable to expect delays so that you don’t feel disappointed if the legal process takes longer than anticipated. Try not to cut costs We understand that buying is a very expensive process. During this time, you might be cautious about your spending in other aspects of your life, so that you can save money where you can. However, it is important not to skip over certain parts of the homebuying process, as this could cost you more further down the line. For example, it may feel like getting a house survey is an avoidable expense, but this vital step highlights any issues with the property that could be costly to repair. Identifying these defects at an early stage may prompt you to renegotiate the purchase price, budget for repairs or even change your mind about buying the property. A step at a time It can be overwhelming to think about the whole homebuying process, so take it a step at a time rather than worrying about moving day before you’ve even placed an offer. That will allow you to focus on what you need to do right now, like attend a viewing or make a mortgage application. It can also help to store all important paperwork, emails and online documents in one place, so the information is easily accessible. Remember why you’re doing it If you’re ever feeling frustrated, remind yourself of the end result. Make sure to celebrate the small milestones, because each step takes you closer to collecting your keys and moving into your new home. You don’t have to navigate the homebuying process alone – we can help alleviate the stress and support you every step of the way. Your home may be repossessed if you do not keep up repayments on your mortgage Source: https://www.mpamag.com/uk/news/general/homebuying-takes-a-mental-toll-on-three-in-five-uk-buyers-research-finds/576591 https://www.barratthomes.co.uk/advice-and-inspiration/is-buying-a-home-stressful/
Research from Yopa indicates that the majority of buyers are looking for homes that require little to no work. According to the survey, 54% of people who bought a home in the last year were only prepared to make minor cosmetic changes to their new home. Meanwhile, 23% were looking for a fully modernised ‘turnkey’ property that was ready to live in. Only 3% were actively seeking a full renovation project and a further 3% were willing to buy a home that needed structural changes. When asked why they did not want to renovate, 21% said they would rather avoid the disruption and 17% wanted to move in quickly. Of the people who were up for a project, 21% said it was so they could benefit from a lower purchase price, while 19% wanted the opportunity to create their own style. Your home may be repossessed if you do not keep up repayments on your mortgage Sources: https://theintermediary.co.uk/2026/06/77-of-homebuyers-seek-properties-requiring-no-work-finds-yopa/ https://londonlovesproperty.com/homebuyers-shun-renovation-projects-as-77-seek-homes-requiring-little-or-no-work/
It can be tempting to delay taking out life insurance or other protection cover, particularly if you are young and healthy and do not feel an immediate need for cover. Some people assume that putting off taking out a policy means saving money because they will pay premiums for fewer years. However, prolonging the decision could actually make life insurance more expensive and reduce the options available to you in the future. The cost of delaying Every life insurance policy is different, depending on the policyholder’s specific circumstances. Your premiums will be calculated based on how much cover you need, your age and general health. As you get older, premiums tend to become more expensive to reflect the increased risk of mortality. You might think that waiting six months won’t make much of a difference to the cost of your policy, but what if you had a health complication within that time? Even a minor change to your health can cause insurers to increase premiums, impose exclusions or reduce the level of cover. Getting a policy sooner rather than later can help secure lower premiums and provide long-term certainty for both you and your family. Consider your wider financial plan Life insurance can play an important role within a financial plan, particularly when it comes to preserving wealth for future generations. From April 2027, unused pension funds will be treated as part of a person’s estate, prompting many people to review their existing arrangements. Because of this, some families are writing life insurance in trust to ensure that beneficiaries are not taxed on the money they receive from their insurance policy. If your family will rely on a life insurance payout to support them after your death, it is particularly important to review your cover now. Thinking of leaving the UK? Life insurance is also worth considering if there is a chance that you may live abroad in the future. Whether you are planning to retire overseas or relocate for work, your residency status can affect your cover. Some policies only insure permanent UK residents, while others may be happy to keep existing cover in place. Taking out a policy well in advance of moving can increase your chances of being eligible for UK protection. It’s therefore advisable to get cover as soon as possible and familiarise yourself with the policy terms. Contact us While delaying a decision about life insurance may seem harmless, it can significantly impact the cost and level of cover you receive. We can help you understand how protection fits into your financial plan. Get in touch for advice. As with all insurance policies, conditions and exclusions will apply Source: https://www.ftadviser.com/content/47c79204-94cc-4a88-b7a3-de16d85d7846
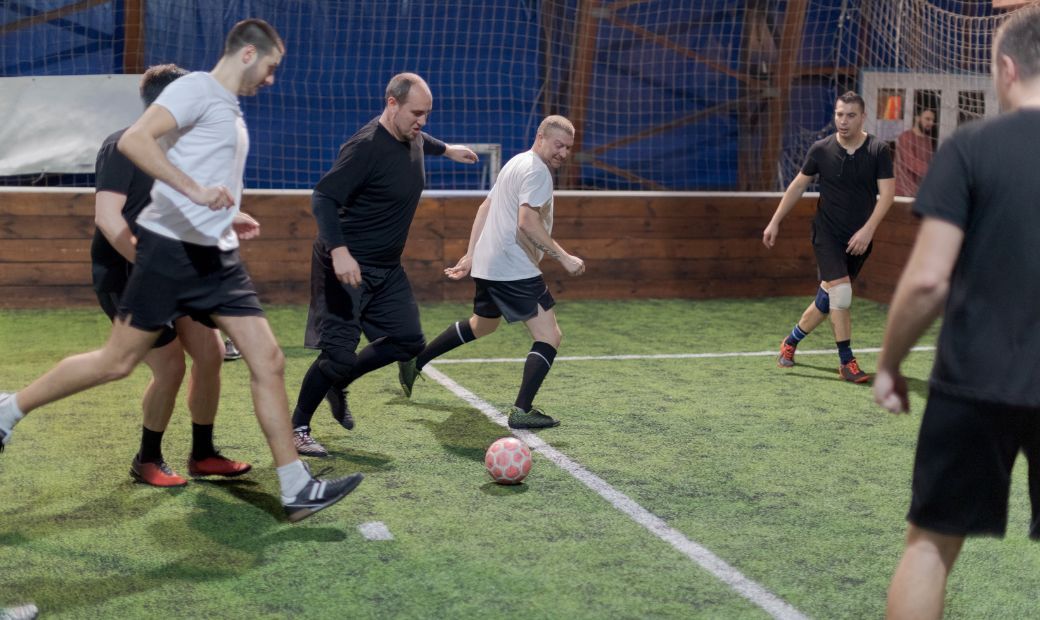
With the World Cup over, many football fans may be inspired to dust off their trainers and join an amateur team. But that comes with a risk of injury… According to research from MetLife UK, nearly a quarter (23%) of UK adults have had a sporting accident. The average person spent four days in hospital after an accident, while one in five stayed even longer. Among those who had experienced or were worried about an accident, the primary concern was taking time off work (23%). One in five (20%) were worried about not being at home for their children, while 16% were concerned about having to take unpaid leave. Having the right protection could alleviate these worries and enable you to live the life you want. As with all insurance policies, conditions and exclusions will apply. Source: https://www.actuarialpost.co.uk/article/football%E2%80%99s-coming-home%E2%80%A6-on-crutches-26686.htm
If you’re packing for a holiday, it’s important to remind yourself which items would be covered if you take them away. When taking your possessions out of the house, it is easy to assume they will automatically be covered under your contents insurance. However, you usually will need to purchase additional cover to insure belongings that you take away from home. Even then, there are times when you won’t be covered, so it’s important to check your specific policy. For example, an item must be carried by you or someone who lives with you in order to be covered. So, if you leave your phone in the care of your friends while you’re on holiday and it gets stolen, you might not be able to make a claim. Or if you drop your phone in the sea, you may not be covered because some insurers don’t pay out for liquid damage. Additionally, possessions left in a hotel room are not always insured, except in cases of forced or violent entry. It’s therefore advisable to keep valuables in a hotel room safe and make sure you have appropriate travel insurance. Don’t leave it to chance - get in touch with us to ensure your possessions will be fully covered while you are out and about in the summer months. As with all insurance policies, conditions and exclusions will apply Source: https://www.admiral.com/resources/home-hub/claiming/personal-possessions-cover-what-youre-covered-for-away-from-home
Younger adults are increasingly taking out life insurance and critical illness cover, according to recent research. Encouragingly, there is growing demand for stand-alone critical illness cover and joint policies among younger buyers, with more under-35s putting protection in place at an earlier stage of life. Research also suggests younger adults are increasingly combining life cover with critical illness protection as awareness of the importance of financial resilience grows. Many younger adults have significant financial commitments, including rent, mortgages and household bills, making financial protection just as important as it is later in life. We can help you explore protection options suited to your needs. As with all insurance policies, conditions and exclusions will apply. Source: https://www.insurancebusinessmag.com/uk/news/life-insurance/younger-buyers-lock-in-cheaper-uk-life-cover-as-protection-market-shifts--report-567434.aspx
Many UK homeowners could be underinsured because rebuild costs are often very different from property values, particularly in certain parts of the country. Property value versus rebuild cost House prices are not simply based on the cost of rebuilding a home. In many areas, values are heavily influenced by location and land prices rather than the bricks and mortar alone. As a result, the rebuild cost of a property can differ significantly from its market value. In some regions, the cost of reconstructing a home after a major disaster could exceed the insured amount by hundreds of thousands of pounds. Research suggests regional variations are becoming increasingly noticeable. In some parts of the UK, particularly where property prices have risen sharply due to demand and location, the market value of homes can be substantially higher than the actual rebuild cost. In other areas, rebuild costs can outweigh property values due to rising construction expenses and local labour shortages. This means homeowners cannot assume their property’s sale price automatically reflects the amount they should insure it for. The underinsurance problem Buildings insurance limits are often linked to property valuations, which can create serious underinsurance risks. If cover is based on an inaccurate estimate, homeowners may find they are not fully protected if they ever need to make a major claim. Recent analysis found that 70% of UK properties are underinsured, while 23% are overinsured, leaving only a small minority insured for the correct amount. The regional divide is also significant. Wales recorded the highest level of underinsurance at 80%, followed by the North West at 77% and Northern Ireland at 75%. Meanwhile, Scotland and the South East reported some of the highest levels of overinsurance. Construction costs, labour shortages and rising material prices have further increased the importance of accurate rebuild assessments in recent years. The cost of materials has fluctuated considerably, while higher energy and transportation costs have also affected the sector. How homeowners can review cover Many homeowners mistakenly assume their insurer will automatically calculate the correct rebuild value. However, this is not always the case, which is why reviewing your cover regularly is so important. Home improvements, such as extensions, can also affect rebuild costs. If these changes are not reflected in your insurance policy, you may not have sufficient cover in place. Having the right level of buildings insurance could help prevent costly shortfalls following major property damage. Speak to us today Get in touch. We can help you to ensure your property has an appropriate level of cover. As with all insurance policies, conditions and exclusions will apply. Sources: https://www.insurancetimes.co.uk/analysis/the-underinsurance-divide-thats-splitting-the-country/1458289.article https://www.chimnie.com/articles/rebuild-costs-hidden-factor-valuations https://www.rebuildcostassessment.com/post/regional-breakdown-uk-insurance-accuracy
New analysis from Stonebridge suggests remortgage activity surged during the opening months of 2026 as borrowers reached the end of ultra-low fixed rate mortgage products arranged during the pandemic. Sharp rise in applications Stonebridge data shows that remortgage applications increased by 45.8% during Q1 2026. The rise comes as many homeowners are reaching the end of fixed rate products arranged when borrowing costs were significantly lower. Many fixed rate mortgages expired during 2025, with a further 1.8 million expected to end this year. As borrowers move onto higher rates, many are reviewing their options to secure a more suitable mortgage arrangement and avoid reverting onto significantly higher standard variable rates. The increase in activity suggests many households are taking a more proactive approach to managing their mortgage costs as financial pressures continue. Borrowers reassessing options The mortgage market has changed considerably since the pandemic era, with interest rates remaining much higher than the record lows seen several years ago. This means many households are facing noticeably higher monthly repayments when their current fixed rate term ends. As a result, more borrowers are actively comparing products and seeking advice before their existing arrangements expire. For some homeowners, even relatively small increases in mortgage rates could significantly affect monthly budgets and wider household finances. The Stonebridge data also showed growing interest in shorter mortgage terms, with two-year fixed products increasing in popularity. This suggests some borrowers may prefer shorter-term flexibility while monitoring future interest rate movements and potential changes to borrowing costs. At the same time, some homeowners are reassessing how long they wish to borrow for, particularly as affordability pressures remain a key concern across the market. Why early planning matters Reviewing your mortgage options before your current fixed rate expires could help you avoid unnecessary increases in monthly repayments. It may also provide an opportunity to reassess your wider financial arrangements and borrowing needs. Many lenders allow borrowers to secure a new mortgage product several months before their existing fixed rate ends, giving homeowners more time to plan ahead. Seeking advice early may also increase the range of products available and reduce the risk of rushed financial decisions closer to expiry dates. Speak to us today We can help you find a mortgage product suited to your circumstances. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. You may have to pay and early repayment charge to your existing lender if you remortgage. Source: https://stonebridgegroup.co.uk/news/mortgage-market-index-46-rise-in-remortgages-in-q1-as-ultralow-pandemic-deals-end/
Many homeowners are still unsure exactly what income protection insurance covers and could therefore potentially miss out on the valuable financial support this protection gives during difficult times. Confusion around cover Research shows that more than a quarter of homeowners wrongly believe income protection policies do not cover mental health conditions. There is also further confusion around eligibility, with some people incorrectly assuming self-employed workers cannot take out cover or that multiple claims are possible. These misconceptions could prevent households from putting appropriate financial protection in place. More support than people realise Income protection insurance is designed to provide regular payments if illness or injury prevents you from working. This support can help households continue covering mortgage payments, bills and other essential living costs. Policies can often cover a wide range of conditions, including both physical and mental health issues, although terms and exclusions will vary between providers. We can help you understand the options available. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. Source: https://healthcareandprotection.com/vast-majority-of-brits-confused-about-what-ip-covers-lifesearch/
Thousands of homeowners may not realise that outdated or unsuitable door locks could affect the validity of their home insurance cover. Security standards matter Research suggests many UK households may not realise their existing door locks and security arrangements no longer meet the requirements set out in their insurance policies. One issue that can lead to claims being rejected is failing to meet minimum door security standards specified by insurers. Most providers specify particular standards for locks, especially on external doors. If these requirements are not met, insurers may reduce payouts or reject claims altogether following a burglary. In many cases, homeowners may be unaware their locks no longer meet current standards, particularly if they have older doors, damaged locks or have not reviewed their home security arrangements for several years. Check your cover carefully Understanding the small print is important, as security conditions and exclusions can differ between insurers and policies. We can help you review your home insurance arrangements and ensure you understand the security requirements linked to your cover. Get in touch now. As with all insurance policies, conditions and exclusions will apply. Source: https://www.businessupnorth.co.uk/home-contents-insurance-fine-print-faulty-door-locks-clauses-leave-northern-homes-uncovered/
Recent research suggests that growing concerns around safety and global instability are encouraging more people to consider protection insurance as a financial safety net. What is the changing sense of security? Research suggests many people feel more vulnerable and uncertain than they did a decade ago. Ongoing geopolitical tensions and concerns around global terrorism are continuing to shape public attitudes towards personal and financial security. The research also found women are more likely to feel uneasy about their personal safety today, with 52% saying they feel more uncertain than they did 10 years ago, compared with 38% of men. Everyday activities are also increasingly contributing to feelings of unease. Research found that 54% of fearful adults no longer feel safe in crowded places, while concerns around travelling abroad and attending large, organised events have also risen sharply in recent months. Travelling alone remains a particularly significant concern for women, with 61% saying they feel less safe doing so, compared with 32% of men. Younger adults are also becoming more aware of the importance of financial protection, with many recognising the pressure that illness, injury or loss of income could place on their households. Why does protection matter? Protection insurance can provide financial support if illness, injury or death affects your ability to earn an income. Depending on the policy, this support can come as a lump sum or regular monthly payments. For many homeowners and families, protection offers reassurance that mortgage payments, bills and everyday living costs could still be managed during difficult periods. In uncertain times, this financial safety net can provide valuable peace of mind. Common forms of protection include life insurance, critical illness cover and income protection insurance. Some policies are designed to help cover mortgage repayments and essential household costs, while others provide support following serious illness or long-term absence from work. As concerns around financial resilience continue to rise, research also suggests more households are taking practical steps to improve their financial security. Four in 10 fearful adults said they had become more interested in protection insurance products during March 2026. The value of professional advice Many people assume protection insurance is too expensive or complicated, but policies can be tailored to suit different budgets and needs. We can help you understand your options and ensure you have appropriate cover in place. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. Source: https://nationalfriendly.co.uk/adviser/bruised-britain/
Home insurance premiums have continued to fall, with average UK premiums dropping by 9% year-on-year in January 2026, according to recent analysis. The improvement follows a significant reduction in severe weather warnings across the UK. Red storm warnings reportedly fell from 18 in 2022 to just four in 2024, while amber warnings also declined sharply over the same period. However, insurers are cautioning households about the risk of wetter-than-average weather and the potential for property damage later in the year. This means reviewing cover levels and policy terms remains important, even as premiums begin to ease. We can help review your options and ensure you have suitable cover in place. As with all insurance policies, conditions and exclusions will apply. Sources: https://theintermediary.co.uk/2026/04/home-insurance-premiums-ease-as-storm-warnings-fall-compare-the-market/ https://www.comparethemarket.com/inside-ctm/media-centre/home-premiums-continue-to-fall-as-households-urged-to-brace-for-wetter-than-average-autumn/

Calls for Stamp Duty reform are continuing to grow as first-time buyers face rising purchase costs. Research suggests first-time buyers have paid an extra £307m in Stamp Duty since the tax-free threshold changed in April 2025. On average, buyers have reportedly paid £4,618 more to complete a purchase over the past year. For many households already struggling with deposits and affordability pressures, Stamp Duty remains another significant barrier to getting onto the property ladder. Industry figures continue calling for reform to help improve affordability. We can help you understand the costs involved with buying a home and explore mortgage options suited to your circumstances. Your home may be repossessed if you do not keep up repayments on your mortgage. Source: https://www.rightmove.co.uk/news/articles/property-news/rightmove-calls-for-stamp-duty-reform/

Many prospective buyers feel ready to move in 2026, but affordability concerns and uncertainty are still causing hesitation. Confidence versus action Research shows that 52% of prospective buyers believe they are ready to purchase a property this year. However, there remains a significant gap between confidence and actually making a move. High property prices and the challenge of saving for a deposit continue to be major barriers for many households. Rising living costs and uncertainty around mortgage affordability have also made it harder for some buyers to feel financially prepared. For first-time buyers in particular, balancing rental costs with saving for a deposit continues to be a significant challenge, despite improving confidence across parts of the housing market. Understanding the process The research also found that 31% of respondents felt they lacked understanding of the homebuying process itself. Many prospective buyers are also unclear about the different mortgage products available. We can help Seeking professional mortgage advice can help buyers better understand their options and feel more confident. We can help you explore suitable mortgage options. Your home may be repossessed if you do not keep up repayments on your mortgage. Source:https://www.mortgageadvicebureau.com/press-releases/four-in-ten-aspiring-homeowners-still-holding-back-despite-rising-confidence/

Going through a divorce can be a very challenging time for you and your family; on top of the emotional stress of separation, there are many practical logistics for you to deal with. Amidst all this, it can be easy to forget about life insurance, but your policy won’t change automatically when you divorce, so it’s important to review it as soon as you can. If you have an individual policy… Even if you and your former partner had separate life insurance policies, you will still need to inform your insurer of your change in circumstances. Divorce can significantly affect your financial situation, so you will need to check if you have the right level of cover for your new lifestyle. You may also wish to review your beneficiaries. If your ex-spouse is still listed, they may remain entitled to a payout unless you update your policy. If you have a joint policy… A joint life insurance will remain in place until you make any changes to it. What you can do next will depend on your insurer and the terms of your policy. In some cases, it may be possible to split the joint policy into two individual policies. If you are not able to do this, there are other options… If your insurer allows it, you could arrange for either you or your ex-partner to take over the existing policy, while the other arranges new cover in their own name. Alternatively, you could cancel the joint policy altogether and both take out new individual cover. However, this may cost more as premiums are typically higher with age. You may also need to submit your medical history again. Plus, if your policy was written in trust, you will need permission from all the trustees before cancelling your cover. Your mortgage and life insurance If your joint life insurance helps protect your mortgage, you and your partner will need to decide what to do next. The person who stays living in your home may be able to take over the policy, but it’s important to ensure the level of cover still matches the outstanding mortgage and their financial circumstances. If the existing policy is no longer suitable, replacing it with a new one that reflects current needs may be necessary. We’re here for you If you’re unsure how your divorce affects your life insurance, speaking to a professional adviser can help you make informed decisions. Get in touch with our team today to review your policy and ensure your protection is right for you. As with all insurance policies, conditions and exclusions will apply. Your home may be repossessed if you do not keep up repayments on your mortgage. Source: https://www.legalandgeneral.com/insurance/life-insurance/family/life-insurance-after-divorce/
